Amarillo 806-371-7661
Pampa 806-665-8429
Hereford 806-364-4686
Write Us a Review

Insights Gallery

When You Should Start Planning to Sell or Transfer Your Business
When You Should Start Planning to Sell or Transfer Your Business

For established business owners, exit planning does not always start with a firm sale date. It often starts when certain changes make the future more concrete. This video explains the key triggers that can signal it is time to begin tax-focused succession or exit planning, including changes in your timeline, a clearer succession path, outside buyer interest, and the start of a real transaction. The goal is to help business owners recognize when waiting may begin to limit their tax, ownership, and deal-structuring options.
Before You Hire Another Employee, Find the Bottleneck
Before You Hire Another Employee, Find the Bottleneck

Business owners should understand where work actually gets stuck and what capacity the business needs. This video explains how to pressure-test a hiring decision by looking at the underlying bottleneck, the role the new employee is meant to play, the expected economic benefit, and the management capacity required to support the hire.
The pro-rata rule: the backdoor Roth IRA mistake that can create an unexpected tax bill
The pro-rata rule: the backdoor Roth IRA mistake that can create an unexpected tax bill

The backdoor Roth IRA strategy can trigger an unexpected tax bill if you overlook the pro-rata rule, which requires the IRS to treat all of your traditional IRA balances together when calculating how much of a conversion is taxable. A separate account, a prior 401(k) rollover, or even a year-end IRA balance you didn't have at the time of conversion can all affect the result. Before contributing or converting, review your full IRA picture to avoid a costly surprise at tax time.
New revenue, donor concentration, and expense allocation: Form 990 issues to watch
New revenue, donor concentration, and expense allocation: Form 990 issues to watch

Changes in revenue, expense allocations, and donor concentration can create Form 990 complications that aren't always visible in the financial statements alone. This article walks nonprofit leaders through three key areas to review before year-end: supporting expense classifications across program, management, and fundraising functions; evaluating whether new income-producing activities trigger unrelated business income tax; and monitoring public-support calculations when donor concentration is rising. Addressing these issues early keeps year-end surprises to a minimum and helps protect your organization's tax-exempt status.
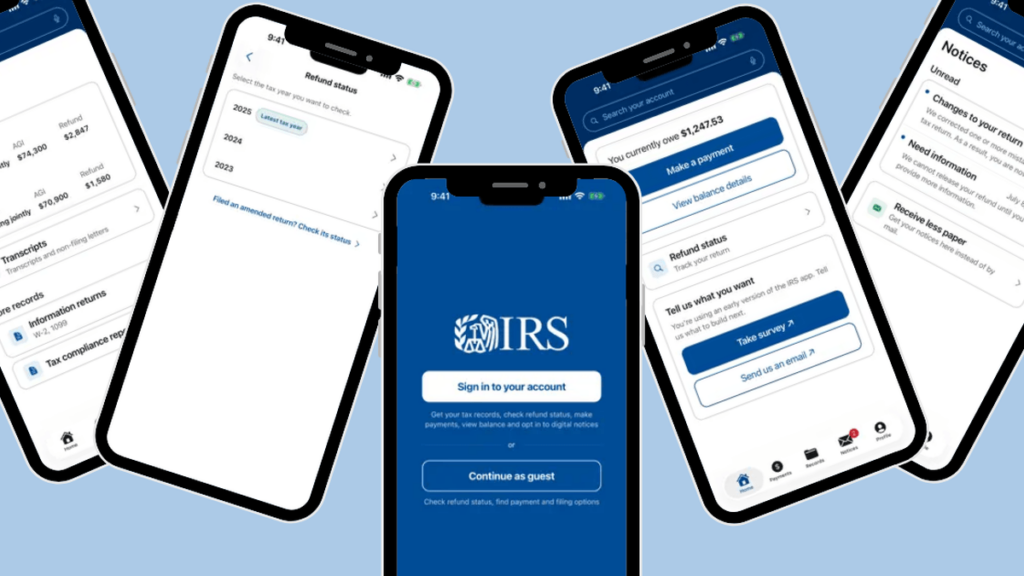
The IRS has a new mobile app. Here’s what taxpayers can do with it.
The IRS has a new mobile app. Here’s what taxpayers can do with it.

The IRS has launched a new mobile app that replaces IRS2Go, giving taxpayers quick access to refund status, payment history, tax records, IRS notices, and Identity Protection PINs. This article walks through what the app can do and how to use it safely. If something in your IRS account raises questions, a tax professional can help you make sense of it.
Prediction Market Taxes: Gambling or Capital Gains?
Prediction Market Taxes: Gambling or Capital Gains?

The IRS has not said how prediction market wins and losses are taxed. See how gambling, capital gain, and Section 1256 treatment could apply.
Q4 tax planning: what needs to happen, and when?
Q4 tax planning: what needs to happen, and when?

Q4 tax planning is not a single deadline; it's a series of decisions that each have their own timing. Some strategies require lead time to execute, others depend on an updated year-end forecast, and some work can legitimately carry into the new year. Knowing which category each decision falls into is what separates effective fourth quarter planning from a last-minute scramble in December.
How much cash should your business actually keep?
How much cash should your business actually keep?

How much cash should your business keep on hand? The answer depends on more than a simple rule of thumb. This article breaks down a practical framework for separating your cash into layers, covering operating needs, committed funds, and contingency reserves, so you can make smarter decisions about liquidity, capital allocation, and when cash truly becomes excess.
Compensation, conflicts, and related parties: what your nonprofit needs to know
Compensation, conflicts, and related parties: what your nonprofit needs to know

Nonprofit boards regularly decide on compensation, vendors, and relationships with affiliated organizations. But when someone with influence stands to benefit, those decisions deserve a closer look. Our latest article walks through the key questions every nonprofit should ask before approving a transaction.
Fraud prevention strategies for nonprofit organizations
Fraud prevention strategies for nonprofit organizations

Nonprofits are disproportionately vulnerable to occupational fraud due to small administrative teams, part-time board oversight, and heavy reliance on cash-based transactions. Asset misappropriation schemes such as skimming, billing fraud, and expense reimbursement abuse are among the most common threats, and the typical scheme goes undetected for over a year. By implementing practical internal controls, strengthening board oversight, and engaging a CPA proactively, nonprofits can significantly reduce their exposure before a loss occurs.
The Quiet Risk of State and Local Payroll Tax Reporting Gaps
The Quiet Risk of State and Local Payroll Tax Reporting Gaps

Payroll tax gaps often emerge when employee work locations and tax reporting fall out of sync. Learn where exposure occurs, what is at risk, and how employers can identify and correct issues before state agencies do.
Retirement Plan Oversight: Four Ways to Reduce Risk

Retirement Plan Oversight: Four Ways to Reduce Risk

ERISA keeps retirement plan oversight with the sponsor. Four ways fiduciaries reduce risk: form a committee, monitor your TPA, assign ownership, act fast.
No results found.

Monday - Friday: 8:00 AM - 5:00 PM
*Will be closed Fridays between Memorial Day and Labor Day
Closed Saturday & Sunday

Subscribe to Our Newsletter

  • Should be Empty:
  • Johnson & Sheldon, PLLC
    Amarillo Location
    500 S Taylor St Suite 200
    Amarillo, TX 79101

    Phone: 806-371-7661
    Fax: 806-371-0529
    Email: ebaten@amacpas.com

    Johnson & Sheldon, PLLC
    Pampa Location
    2004 N. Hobart
    Pampa, TX 79065

    Phone: 806-665-8429
    Fax: 806-665-8804
    Email: blewis@amacpas.com

    Johnson & Sheldon, PLLC
    Hereford Location
    119 E 4th St
    Hereford TX 79045

    Phone: 806-364-4686
    Fax: 806-364-0826
    Email: khollingsworth@amacpas.com
    President’s Award
    35 Years

    Johnson & Sheldon, PLLC, is proud to be part of Aprio Alliance — a national association created by accounting professionals to help collaborative, growth-minded CPA firms thrive. This affiliation gives us access to leading expertise, resources, and best practices, while preserving what matters most: the personalized service and local insight you expect from an independent firm. Joining Aprio Alliance reinforces our commitment to exceptional client service and staying ahead of industry trends. While we leverage the strength of a national firm, we remain fully independent—maintaining our name, client relationships, and service approach.